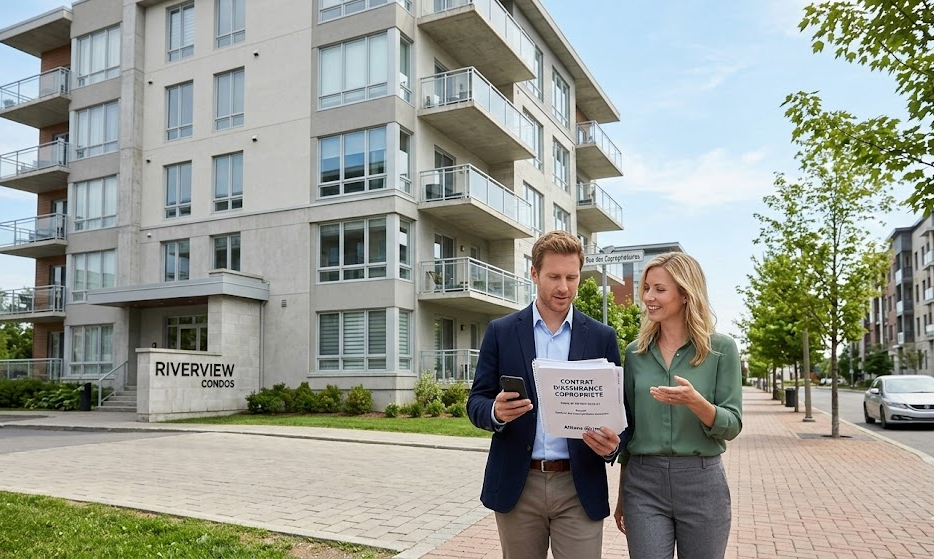
Owning a condominium presents a unique blend of benefits and responsibilities. While you enjoy the comforts of home and the community atmosphere a condo offers, ensuring your investment is protected is crucial. Condominium insurance, commonly known as HO-6 insurance, is tailored for unit owners, providing essential coverage that complements the master policy held by your condo association.
What Is Condominium Insurance?
Condominium insurance is designed specifically for the individual needs of condo owners. It typically covers personal belongings, improvements made to the unit, and liability within your space. While your condo association usually maintains a master policy that protects the building’s structure and common areas, it often falls short of covering your personal items and unit upgrades. Thus, understanding what your individual policy includes is paramount.
Key Coverage Areas in Your Condo Insurance Policy
When evaluating your condo insurance, it’s essential to know what specific areas are protected under the policy. The primary components usually include:
- Personal Property Coverage: This protects your belongings, such as furniture, electronics, and clothing, against losses due to theft or damage. You have the choice between Replacement Cost Value (RCV), which compensates you for the cost of replacing items, and Actual Cash Value (ACV), which takes depreciation into account.
- Dwelling Coverage: This covers the interior structure of your condominium, including walls, floors, and built-in fixtures. If any damage occurs within your unit, this coverage assists in covering repair costs.
- Liability Protection: Liability coverage comes into play if someone sustains injuries while in your condo. This aspect provides legal defense and medical coverage, safeguarding your finances from significant claims.
- Loss of Use Coverage: Should your condo become uninhabitable due to damages, this protection covers additional living expenses like hotels and meals during the repair period.
- Loss Assessment Coverage: In situations where communal damages exceed the master policy’s limit, this coverage helps you handle any additional costs that may arise.
How Does a Master Policy Affect Your Coverage?
You may be asking yourself, “If my condo association has a master policy, why do I need my own insurance?” The answer lies in the division of responsibilities. The master policy generally covers the building’s exterior and shared spaces but leaves the area inside your unit vulnerable.
Types of Master Policies Explained
Understanding the specific type of master policy your association holds can significantly influence how you choose your own coverage:
- Bare Walls-In Policy: Covers only the basic structure of the unit, leaving all interior items uninsured.
- Single Entity Policy: Covers originally built fixtures and common areas but not personal upgrades.
- All-In Policy: Protects both inherited and personal improvements, but you’ll still need to insure your personal belongings.
Choosing the Right Condo Insurance for Your Needs
Determining the right level of coverage is not a one-size-fits-all process. Your unique lifestyle, hobbies, and valuable items should guide your decision. Here are some strategies:
- Global Assessment: Start by cataloging everything you own. This inventory helps in gauging your insurance needs accurately. Don’t forget those high-value items that may require special riders for full coverage.
- Consider Your Lifestyle: If you host frequently or if you have children or pets, higher liability coverage may be prudent.
- Effective Deductible Planning: A deductible is the out-of-pocket amount you’ll need to pay before your insurance kicks in. Balancing your deductible with your premium is critical.
Dispelling Common Misconceptions about Condo Insurance
Let’s clarify some frequently held myths about condo insurance that can lead to confusion:
- Myth 1: “I don’t need condo insurance because the master policy covers everything.” This is misleading—the master policy doesn’t cover personal belongings or your liabilities.
- Myth 2: “Condo insurance is too expensive.” The actual cost often depends on various factors, including the building’s age and your location. Discounts can significantly reduce your premium.
- Myth 3: “A condo policy covers all types of damage.” Standard policies typically don’t cover natural disasters like floods or earthquakes, so consider additional coverage if in a prone area.
Additional Coverage Considerations with Condo Insurance
Beyond the basic coverage, consider exploring optional add-ons that can enhance your protection:
- Water and Sewer Backup Coverage: Sudden water damage from bursting pipes can be covered, but sewer backups often require specific provisions.
- Earthquake Coverage: Standard insurance does not typically include this. If you live in a region prone to seismic activity, this add-on is worth investigating.
- Legal Expense Insurance: This can cover legal fees for specified disputes, adding an extra layer of defense for your financial stability.
Final Thoughts
Understanding condominium insurance coverage is essential for safeguarding your property and personal belongings. Consult with an insurance expert to ensure you select a policy that meets your unique needs and fills the coverage gaps left by your association’s master policy.